Two Roofs, One Balance Sheet: Underwriting a Second UK Premises
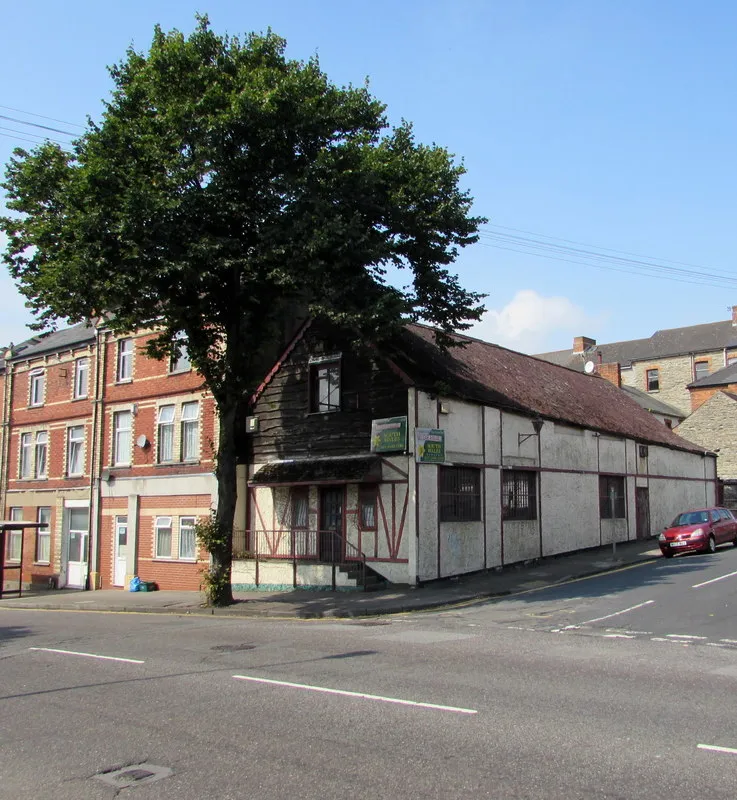
Photo: Jaggery , CC BY-SA 2.0, via Wikimedia Commons
Opening a second premises rarely begins as a spreadsheet decision. It usually begins as a feeling: the unit looks right, the high street feels busy, and the landlord's rent-free period expires on Friday. The commercial task is to convert that feeling back into a set of testable assumptions. For an owner-led UK SME, the most useful mental model is not 'expansion'. It is an acquisition — of a fixed-cost base, a local demand pool and a management burden — and it deserves the same scepticism you would apply to buying a competitor.
The terms sheet is a hypothesis, not a forecast
A landlord's terms sheet describes what the landlord would like to happen. It is not evidence that the site will work. Treat every line — rent, rent-free period, service charge, repair obligation, break clause — as a claim to be tested. The useful question is not 'can we afford the rent?' but 'what would have to be true for this site to pay for itself, and how would we know before we are committed?'
Five figures do most of that work. They are not precise forecasts. They are tests of whether the opportunity survives contact with arithmetic.
Figure one: the full annual cost of occupancy
Rent is the visible number and rarely the largest one. Build the occupancy cost from the ground up: base rent, business rates, service charge, insurance rent, utilities, waste, compliance and licensing, and the amortised cost of fit-out. Add professional fees, signage, IT and a contingency of at least 10 per cent.
Business rates deserve particular attention. Rateable values, multipliers and reliefs differ across England, Wales and Scotland, and small business rates relief may not follow you to a second site in the way you expect. Check the rateable value, the relief position and the appeals route before you model the cost. Service charge demands should be accompanied by a budget and a reconciliation; ask what is capped and what is not.
Fit-out should be divided by the lease term, not by the useful life of the fixtures. A 10-year lease with a five-year fit-out cycle carries a different annual burden from a five-year lease with the same spend. Add an estimate for dilapidations at exit, informed by a schedule of condition agreed at the start. Express the total as an annual, monthly and weekly figure. The weekly figure is the one that will govern your mornings.
Figure two: demand you can evidence, not demand you can imagine
A catchment is easy to describe and hard to prove. Drive times, footfall, competitor density, parking, transport links and the mix of nearby occupiers all matter, but none of them is a sales forecast. Landlord footfall data is marketing material until you have seen the raw counts, the dates and the method.
Look for a cheap test before a costly commitment. A pop-up unit, a market stall, a click-and-collect point run from the existing site, a delivery radius or a short outbound calling campaign in the target postcode can all generate evidence. Compare the result with the first year of your existing site, not its mature year. Ask what would have to be true for demand to come in 30 per cent below the estimate, and whether the site would still be viable. If the answer is no, the estimate is doing too much work.
Figure three: management cover for the days you cannot be in both places
The owner's time is the cost that rarely appears in the lease. A second site does not simply divide your attention; it creates a new middle layer of supervision, scheduling and escalation. Decide who covers opening, closing, Saturdays, holidays and sickness, and what that cover costs. Recruitment for a supervisor or assistant manager can take weeks, and a weak appointment in the first quarter is expensive to unwind.
There is also an opportunity cost. Every day spent at the new site is a day not spent on the existing one. If the first site's performance depends on your presence, the second site is partly funded by a risk to the first. Budget for management cover from day one rather than assuming you will absorb it.
Figure four: the weekly break-even the site must hit
Annual budgets hide the rhythm of a new site. Convert the occupancy cost and the additional staffing into a weekly fixed-cost figure, then calculate the sales required each week to cover it at your expected contribution margin. Compare that figure with the realistic opening hours and the catchment's weekly pattern. A site that needs £6,000 a week and opens five days a week is a different proposition from one that needs the same amount over seven days.
Assume a ramp. Very few second sites reach mature sales in the first quarter. Model the first two quarters at 50 to 60 per cent of the mature estimate and calculate the cash burn at that level. Set a review trigger in advance: if weekly sales remain below a stated threshold for eight consecutive weeks, the site goes to a formal review with options — renegotiate, sublet or exit — rather than drifting.
Figure five: the cash buffer for a slow start
A second site consumes cash before it produces it. The deposit, legal fees, fit-out overruns, opening stock, recruitment and the gap between sales and cash collection all arrive early. Quarterly rent and VAT timing can bunch in the same month. The buffer should cover four to six months of fixed costs plus a working-capital allowance, and it should be cash or a committed undrawn facility — not a loan you hope to arrange under pressure.
Personal guarantees are common in SME leases. If you are asked to give one, treat it as part of the cost of the deal and negotiate its scope and duration. A guarantee that survives the break clause is a different risk from one that falls away on exit.
Negotiate the exit before you fall in love with the unit
The most valuable clause in a second-site lease is often the break. A break at 24 or 36 months, with three to six months' notice and a defined penalty, converts a long bet into a staged one. Rent-free periods should be aligned with fit-out and opening, and you should check whether rates and service charge remain payable during the free period. Caps on service charge, turnover-based rent, a schedule of condition, limited assignment rights and an option — not an obligation — to extend are all worth agreeing in heads of terms, before solicitors are instructed.
A one-page decision memo
Summarise the five figures on a single page: full annual occupancy cost, evidenced demand range, management cover cost, weekly break-even and cash buffer. Add the walk-away thresholds and the name of the person who owns each number. If the memo cannot be written without optimistic assumptions, the site is not ready. The calm commercial answer is not always no, but it is almost always 'not yet, and here is what would change our mind'.